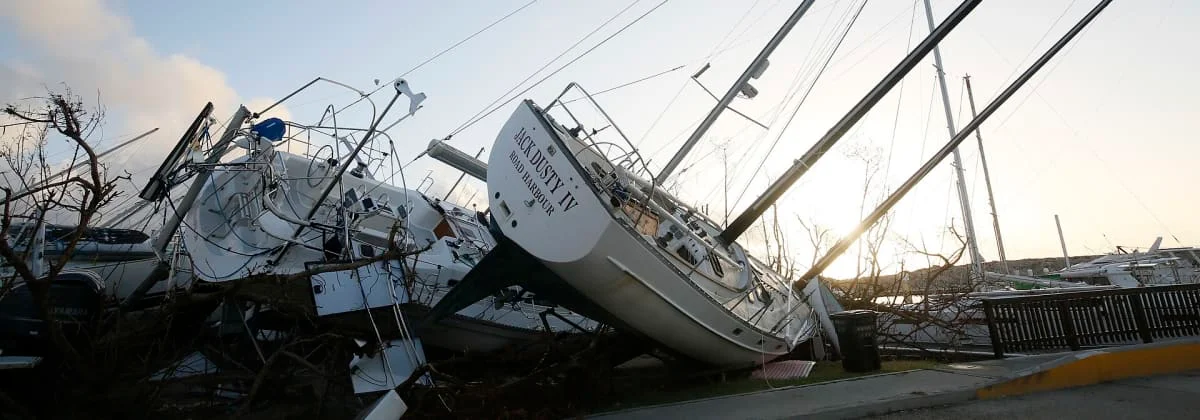
Quick answer: There is no single industry-wide boat insurance hurricane box map, each marine insurer draws its own geographic limits on your policy chart. In practice, the box usually covers coastal Florida, the US Gulf, and selected Caribbean islands where named-storm deductibles (often 2-5% of hull value), filed hurricane plans, and 48-72 hour execution windows apply. Lay-up credits commonly start north of latitude 34°N outside the box from June through November.
Read your hurricane plan before June 1, not during a warning
Send your hull value, flag, and where the boat sits in season. We tell you which clauses decide whether a storm claim gets paid, and introduce underwriters who write storm-exposed risks.
Why Hurricane Zones Change Yacht Insurance Completely
The Yacht Insurance Guide introduces H&M and P&I. For windstorm deductible percentages and flat-amount examples by hull value, see the named storm deductible guide. This page focuses on the contractual machinery that determines whether a storm claim gets paid. Two owners with identical $400,000 motor yachts in the same marina can have wildly different outcomes after a hurricane, one complied with a plan and documented preparations; the other stayed on a floating dock with single lines and lost cover.
Geographic scope of hurricane zone underwriting:
| Region | Peak season | Primary perils |
|---|---|---|
| South Florida and Keys | June 1 to Nov 30 | Surge, wind, marina pile failure |
| US Gulf Coast (TX to AL) | June 1 to Nov 30 | Surge, river flooding, yard capacity |
| Bahamas and Turks & Caicos | Aug to Oct peak | Surge in shallow anchorages, mooring drag |
| Eastern Caribbean (BVI, USVI, Antigua) | Aug to Sep peak | Mooring field damage, limited haul-out |
| Western Caribbean (Belize, Yucatán) | Sep to Oct | Lagoon surge, cyclone tracks |
Premiums in these regions run higher than temperate cruising areas, often 1.0-2.5% of hull value or more for private pleasure craft, before windstorm deductible structure. Exact rates depend on vessel age, marina exposure, and owner experience. For Florida-specific marina lease alignment and Broward/Miami rating factors, read Yacht Insurance Florida alongside this pillar page. Owners selling before storm season should also review Selling a Yacht in Florida, buyers discount vessels without haul-out logs or approved hurricane holes.
On a $400,000 motor yacht in a South Florida marina, a 3% windstorm deductible means the owner pays the first $12,000 of any named-storm claim before hull cover responds, separate from the standard $2,500-$10,000 deductible on other perils. At a 5% windstorm loading on a $600,000 boat, the first $30,000 of any partial loss sits with the owner, which makes small claims uneconomic to pursue. Premiums in hurricane zones often run 1.0 to 2.5 percent of hull value or more for private pleasure craft before windstorm structure. Two identical yachts in the same marina can see opposite claim outcomes: one owner executed an approved hurricane plan with photos and timestamps; another stayed on a floating dock with single lines and lost named storm cover.
Where Is the Hurricane Box on Your Policy?
Owners searching for a hurricane box map usually want one chart that shows where boat insurance storm rules start. Marine underwriters do not publish a universal map. Instead, your policy navigational limits and named-storm endorsement define the box, a set of coordinates, coastlines, or island groups where hurricane-plan compliance and windstorm deductibles apply.
How to read your insurer’s box (binder checklist):
| Document section | What to look for |
|---|---|
| Navigational limits / cruising range | Coasts and island chains where cover is active |
| Named-storm or windstorm endorsement | Geographic trigger box tied to NHC advisories |
| Hurricane plan schedule | Approved marinas and yards inside the box |
| Lay-up or seasonal navigation clause | Latitude line (often 34°N) for premium credits outside peak exposure |
| Exclusions | Areas explicitly outside cover (e.g. specific lee shores, unnamed anchorages) |
Typical hurricane box boundaries (planning map, confirm in your policy):
| Zone | Commonly included in US coastal storm boxes | Often outside standard in-water season terms |
|---|---|---|
| South Florida and Keys | Yes, full named-storm machinery | North of 34°N with documented lay-up |
| US Gulf (TX to AL) | Yes, surge and yard-capacity risk | Northern Chesapeake summer berth |
| Bahamas (selected banks) | Often yes with approved plan | Maine / Nova Scotia summer storage |
| Eastern Caribbean (BVI, USVI, Antigua) | Frequently yes, limited haul-out | US East Coast above 34°N |
| Southern Caribbean (Grenada, Trinidad) | Sometimes partial or sub-limited | Depends on insurer chart |
| US East Coast north of Virginia | Often reduced storm loading | May still have nor’easter perils |
Latitude reference owners use most:
- 34°N, frequent lay-up credit line (roughly Cape Hatteras / Virginia Beach latitude). Vessels stored north of this line June 1, November 30 may qualify for reduced hurricane-season premium if the insurer credits off-season navigation.
- 25°N, common southern boundary for “full” Florida/Gulf storm pricing on pleasure craft policies.
- Policy-specific boxes, some binders use a rectangle from Brownsville TX to Maine, others exclude the Carolinas in-water unless a plan is filed.
Practical map workflow before June 1:
- Print or save the nav limits page from your binder and mark your home marina.
- Overlay your hurricane plan secondary location: haul-out yard or hurricane hole must sit where the policy allows.
- If you cruise across boxes (Florida summer, Caribbean winter), request split-season wording so you are not in breach the day you cross the Gulf Stream.
- Ask your broker for the insurer’s sample hurricane plan template: it often sketches the geographic box in plain language even when the chart is legal-heavy.
Entering the box without an approved plan, or staying in-water in a high-exposure sub-zone when your plan requires haul-out, is how named-storm claims fail, regardless of how carefully you doubled dock lines.
What Has to Be in a Written Hurricane Plan?
A hurricane plan is not a vague intention to “move the boat if it looks bad.” It is a filed document, sometimes insurer-supplied template, sometimes owner-drafted, that identifies:
- Primary berth during season and its wind exposure rating
- Secondary location, hurricane hole, inland marina, or haul-out yard
- Mooring protocol, number of lines, chafe protection, anchor setup
- Responsible party, owner, captain, or marina contractor
- Equipment removal, sails, bimini, dodger, tender lifting
- Timeline, actions at watch vs warning stages
Hurricane plan checklist before filing:
| Item | Detail to include |
|---|---|
| Vessel identification | Documentation number, LOA, beam for haul-out slots |
| Season berth contract | Marina agreement allowing storm prep |
| Haul-out yard reservation | Priority list status or guaranteed slot |
| Inland marina alternative | Distance from coast, surge exposure |
| Fuel and power | Tank level, shore power disconnect procedure |
| Crew availability | Who executes if owner is travelling |
| Travel lift capacity | Verified for vessel weight and beam |
| Bridge and canal constraints | Air draft and lock schedules for relocation |
Submit the plan when binding cover; see the Yacht Insurance Checklist for pre-bind steps. Update the plan if you change marinas mid-season; stale plans breach warranty.
Insuring a yacht in Florida or the Caribbean?
Compliance is decided at binding, not after the storm is named. Send hull value and intended season berth and we will flag the plan requirements likely to apply before you request quotes.
When Does Your Hurricane Plan Have to Be Executed?
Hurricane plan triggers are written into the policy and are usually earlier than owners expect. Common structures activate on a tropical storm watch for the county or mooring zone, giving 48 to 72 hours to complete a haul-out or relocation that yards are simultaneously being asked to do for everyone else.
- Tropical storm watch issued for your county or mooring zone
- Hurricane watch within 150 nautical miles
- Entry of storm centre into a geographic box on insurer map
- Official warning from US National Hurricane Center or equivalent
Once triggered, owners typically have 48-72 hours to complete relocation or securing. Build personal triggers 24 hours earlier, haul-out yards fill, bridges lock down, and fuel queues form.
Execution decision tree:
| Stage | Action |
|---|---|
| Storm invest / distant track | Monitor; confirm crew and yard on standby |
| Watch issued | Begin relocation or haul-out scheduling |
| 72 hours to landfall | Vessel should be in approved secondary location or secured per plan |
| 48 hours | All canvas removed; tenders lifted; lines doubled |
| 24 hours | Shore power disconnected; seacocks checked; photos taken |
| Post-storm | Document damage before moving; notify insurer immediately |
Failure to meet the window is not forgiven because the marina was full, that is exactly the scenario the plan is meant to pre-solve.
How Much Is a Named-Storm Deductible in Dollars?
Standard hull deductibles ($2,500-$10,000) often do not apply to named-storm claims. Windstorm deductibles are separate.
| Hull value | 2% windstorm ded. | 3% windstorm ded. | 5% windstorm ded. |
|---|---|---|---|
| $200,000 | $4,000 | $6,000 | $10,000 |
| $400,000 | $8,000 | $12,000 | $20,000 |
| $750,000 | $15,000 | $22,500 | $37,500 |
| $1,200,000 | $24,000 | $36,000 | $60,000 |
On partial losses, dock collision, rigging damage, water intrusion, you absorb the windstorm deductible first. On a $50,000 repair after a named storm, a 3% deductible on a $600,000 boat ($18,000) can exceed the repair bill, making small claims uneconomic.
Compare windstorm terms when quoting, a lower annual premium with a 5% windstorm deductible may cost more over time than a moderate premium with 2% and lay-up credits.
Model premium and deductible trade-offs in the yacht insurance cost calculator before binding.
Florida and the Gulf Coast: What Underwriters Require
Florida-specific considerations:
- Floating docks, higher drag risk; insurers may require relocation vs in-water tie-up
- Canal mooring, surge can overwhelm seawalls; inland canal is not automatic safety
- Stack storage, some insurers credit properly racked vessels; others require contractual haul-out
- Liveaboards, restrictions on occupancy during warnings may appear in marina and policy terms
- Bridge closures, Miami and ICW constraints affect relocation timing
Marina costs interact with storm strategy. Compare Marina Berth Cost Guide pricing against haul-out fees for peak months, sometimes storing in a hurricane-rated yard June through November costs less than premium loading for in-water season berthing.
Lenders financing Florida vessels require continuous hull cover through hurricane season. Read the yacht financing guide for covenant timing if you plan lay-up credits.
Caribbean Storm Prep: Island by Island
Caribbean storm prep realities:
| Location | Infrastructure challenge | Insurance implication |
|---|---|---|
| BVI mooring fields | Mooring ball quality varies | Plan may require marina berth or departure |
| Grenada (south) | Below main hurricane belt | Sometimes lower premium; confirm policy box |
| Bahamas banks | Shallow surge | Relocation to protected creek or Florida haul-out |
| USVI | Limited haul-out | Early departure to Puerto Rico or US mainland |
| Belize | Lagoon access | Cyclone tracks; narrow weather windows |
Charter fleets in the Caribbean face overlapping season and storm peaks; if you charter, combine this guide with Charter Yacht Insurance for guest liability during storm evacuation.
Some owners execute a seasonal migration, Caribbean winter, Maine or Chesapeake summer, which can reduce annual premium if underwriters credit the lay-up period. Document northern arrival dates for renewal audits.
How to Earn a Lay-Up Credit North of 34 Degrees
Lay-up credits of 10-25% on the hurricane-season portion of premium are common, but only against actual compliance. The conditions are specific: north of latitude 34N or the insurer’s own line by 1 June, haul-out or ashore storage confirmed, engines not operated inside the hurricane box during the lay-up period, and the insurer notified if the vessel re-enters early. GPS tracking and marina invoices may be requested at renewal.
- Vessel north of latitude 34°N (or insurer-specific line) by June 1
- Haul-out or ashore storage confirmed
- Engines not operated in hurricane box during lay-up period
- Notification to insurer if vessel re-enters early
Credits of 10-25% on the hurricane-season portion of premium are common, but only if you actually comply. GPS tracking and marina invoices may be requested at renewal.
Who benefits most:
| Owner profile | Lay-up strategy |
|---|---|
| Snowbird cruiser | Natural fit, summer north, winter south |
| Florida resident | Haul-out or inland yard for peak months |
| Caribbean liveaboard | Harder, may need full-season storm pricing |
| Charter operator | Limited lay-up; active season is hurricane season |
Lay-up credits of 10-25% on the hurricane-season portion of the premium are common where the vessel sits north of 34°N by 1 June with confirmed haul-out or ashore storage. A snowbird cruiser who summers in Maine and winters in Florida may qualify if GPS tracking and marina invoices support compliance at renewal. Failure to meet the forty eight to seventy two hour execution window after a tropical storm watch is not forgiven because the haul out yard was full. Build personal triggers twenty four hours earlier because yards fill, bridges lock down, and fuel queues form. Documentation after major storms should include photo logs with timestamps, marina invoices for haul out labor, weather screenshots at execution time, and captain statements if crew acted without the owner present. Insurers investigate plan compliance before adjusting claims.
What to Document Before and After a Named Storm
Claims are settled on evidence created before the storm, not after it. Build a six-part record: a wide-shot photo log of berth, lines, chafe guards and tender storage; visible timestamp metadata; marina invoices for haul-out and priority storm-prep labour; emails confirming the yard reservation; weather screenshots showing the watch or warning at the time you acted; and a captain’s statement if crew executed the plan without you.
- Photo log: wide shots of berth, lines, chafe guards, tender storage
- Timestamp metadata: phone photos with date/time visible
- Marina invoices: haul-out, priority storm prep labour
- Communication records: emails confirming yard reservation
- Weather screenshots: watch/warning at time of execution
- Captain statement: if crew executed plan without owner present
Prompt notice matters, policies require reporting within defined periods after loss. Delayed notice gives insurers a denial argument even when damage is clear.
For total losses involving other vessels, P&I may activate for third-party damage your boat caused while dragging, another reason P&I limits matter in crowded marinas.
Still deciding between lay-up and staying in the box?
Underwriters approve realistic plans before the season starts. Send both scenarios and we will help you compare the premium against the haul-out and repositioning cost.
Red Flags in a Hurricane-Zone Quote
Three quote defects signal an incomplete submission rather than a competitive price. A Florida policy with no written hurricane plan requirement, a 5% windstorm deductible with no stated basis, and storm terms deferred to binding all mean the real cost is not yet visible.
Negotiate or walk away if you see:
- No written hurricane plan requirement on a Florida policy: likely incomplete quote
- 5% windstorm deductible without premium offset vs competitors
- Surge excluded at dock: critical in South Florida
- 72-hour window with no haul-out reservation possible in your marina
- Geographic box that excludes your actual mooring island
- Lay-up credit promised verbally but not in binder wording
- Captain requirement you cannot staff during storm season
- Automatic void if vessel in hurricane box any day June to November: read carefully
Budgeting Storm Strategy Into Annual Ownership Cost
Storm strategy is a budget decision as much as an insurance one, because the cheaper premium usually buys a more expensive summer. Higher in-water Florida season premium, haul-out and yard fees, and northward relocation each trade against the others and belong in one annual figure.
Budget holistically in the yacht ownership cost guide:
- Higher premium for in-water Florida season
- Haul-out and yard fees vs lay-up credit savings
- Relocation fuel and crew costs for storm moves
- Windstorm deductible self-insurance reserve
- Lost cruising days during evacuation
Owners who treat hurricane planning as operational routine, not insurance paperwork, fare better in both claims and renewal pricing.
Frequently Asked Questions
A hurricane plan is a written document required by many marine insurers as a condition of cover in Florida, the Gulf of Mexico, and the Caribbean. It specifies where the vessel will be moved or how it will be secured when a named tropical storm or hurricane threatens, including target marinas, haul-out yards, mooring configurations, and responsible crew. Insurers may require plan execution within 48-72 hours of a defined trigger.
Failure to implement an approved hurricane plan as specified in the policy can void named-storm damage coverage, including total loss from surge, wind, or dock collision. Insurers investigate whether the owner took reasonable steps within the required timeframe. Document your preparations with photos and timestamps to support claims if you complied.
Windstorm or named-storm deductibles in hurricane zones are often higher than standard hull deductibles, commonly 2% to 5% of agreed hull value, or a flat amount such as $10,000-$25,000. On a $500,000 yacht with a 3% windstorm deductible, the owner pays the first $15,000 of any named-storm claim regardless of the standard $5,000 deductible on other perils.
Many marine insurers offer lay-up credits when the vessel is stored north of a defined latitude, often 34°N or outside the hurricane box, during peak season (typically June 1 through November 30). Credits vary by insurer and may require proof of haul-out or a northern marina contract. Ask your broker to quote both full-season and lay-up scenarios.
Coverage depends on navigational limits and hurricane plan compliance. Caribbean policies from US and Lloyd's insurers often include named-storm requirements similar to Florida, pre-approved mooring or haul-out locations, line-doubling protocols, and removal of sails and canvas. Confirm whether your policy covers the specific island chain and whether surge at dock is included or sub-limited.
Policies define triggers differently, some at tropical storm watch, others at hurricane warning or when the storm enters a geographic box. Read your binder for the exact trigger and countdown window. Build your personal decision tree to act at least 24 hours before the insurer's minimum deadline to account for haul-out yard queues and bridge closures.
Some insurers maintain lists of approved hurricane holes, haul-out facilities, and high-wind-rated marinas. Others accept owner-written plans if the location meets wind exposure and surge criteria. Before binding cover, confirm your planned marina or yard is acceptable, switching mid-season without insurer approval can breach warranty.
The hurricane box is the geographic area defined in your policy where named-storm rules apply, often coastal Florida, the Gulf of Mexico, and parts of the Caribbean. Outside the box, standard deductibles may apply; inside it, windstorm deductibles, hurricane plans, and execution windows typically bind. Each insurer draws the box differently, read your navigational limits and storm endorsement maps in the binder, not a single industry-wide chart.
It can, but only when three conditions hold at the same time. The named-storm peril has to be included rather than excluded or sub-limited, the vessel has to be inside the navigational limits on the policy at the time of loss, and the filed hurricane plan has to have been executed as written within the required window. Where all three hold, surge, wind, and dock-collision damage are typically covered subject to the windstorm deductible rather than the standard hull deductible. Where the plan was not executed, insurers can and do decline named-storm claims outright, including total losses.
Premium depends on hull value, vessel age and construction, your claims record, the crew or captain arrangement, and above all whether you stay in the box during season or lay up outside it, so any single figure quoted without those inputs is guesswork. The number you can pin down in advance is your retained risk. On a $500,000 hull, a 2% named-storm deductible is $10,000, 3% is $15,000, and 5% is $25,000, and that applies before any premium comparison. Ask your broker to quote a full season inside the box and a lay-up scenario side by side, then weigh the premium difference against the haul-out and repositioning cost.
It is not a rule of law, it is a common underwriting line. Many marine insurers grant a lay-up credit when the vessel is kept north of latitude 34 degrees north, roughly Cape Hatteras, or otherwise outside the hurricane box, during peak season from about June 1 to November 30. Some insurers draw the line elsewhere, and some require documented haul-out or a northern marina contract rather than position alone. Treat 34 degrees as the industry shorthand and your own binder as the authority.
Request a yacht buyer consultation
Share your budget, target LOA, and use case. We reply within one business day with matched brokers or surveyors.